

Tax season creates additional pressure for CPA firms. While preparing tax returns, accounting teams must also review client records, reconcile bank accounts, investigate missing transactions, and resolve year-end bookkeeping issues. When several clients submit their financial records at the same time, these tasks can compete with the firm's tax preparation deadlines.
This is one reason CPA firms outsource bookkeeping during tax season. By assigning selected accounting tasks to an external team, Firms can handle increased bookkeeping workloads without putting additional pressure on their in-house teams to manage every transaction and reconciliation.
The arrangement works best when responsibilities are clearly defined. An outsourced bookkeeping team can record transactions, reconcile accounts, maintain general ledger records, and prepare supporting schedules. The firm's in-house team can review the completed work, resolve any outstanding questions, and focus on tax-related decisions.
Understanding which tasks to outsource and how to manage the working relationship helps CPA firms determine whether outsourced bookkeeping is suitable for their seasonal workload.
Why Bookkeeping Work Increases During Tax Season
Tax preparation depends on financial records that are complete, organized, and ready for review. However, many businesses do not maintain their books consistently throughout the year.
Some clients provide accounting records every month. Others submit several months of bank statements, receipts, invoices, and expense information shortly before their tax preparation appointment.
These differences create additional work for CPA firms.
For example, a business client may have recorded most of its transactions but still have unreconciled bank accounts, uncategorized expenses, and outstanding customer balances. Before the CPA can rely on the financial information, the bookkeeping records may need further review.
Common issues include:
- Unrecorded transactions: Bank activity or credit card charges have not been entered into the accounting system.
- Incorrect expense classifications: Transactions have been posted to unsuitable general ledger accounts.
- Unreconciled accounts: Recorded balances do not agree with bank or credit card statements.
- Outstanding client information: Receipts, invoices, payroll records, or explanations for unusual transactions are missing.
- Incomplete year-end records: Account balances and supporting schedules need review before tax preparation.
These tasks require time from accounting staff. When they arise across several client accounts during the same period, firms may need additional bookkeeping capacity to keep their workflows moving.
Why CPA Firms Outsource Bookkeeping During Tax Season
Outsourcing is not simply a way to transfer transaction entry to another team. It allows CPA firms to organize accounting responsibilities according to the type of work involved and the level of professional review required.
1. Manage Seasonal Workloads Without Permanent Hiring
CPA firms may experience a significant increase in work during tax season. The additional workload can include year-end bookkeeping, financial statement preparation, tax return preparation, and client follow-ups.
Recruiting permanent employees to handle every temporary increase may not be suitable for smaller firms or practices with fluctuating workloads.
Outsourced bookkeeping services provide another way to increase processing capacity. Firms can assign specific activities to an external team based on transaction volumes, client requirements, and agreed deadlines.
For example, a CPA firm may retain responsibility for client communication, complex account adjustments, and final reviews while an outsourced team handles transaction recording and routine bank reconciliations.
This arrangement gives the firm access to additional bookkeeping resources without automatically expanding its permanent workforce.
The firm should still consider onboarding time, management requirements, provider fees, and the cost of reviewing completed work when comparing outsourcing with internal hiring.
2. Get Client Books Ready for Tax Preparation
Incomplete bookkeeping records can delay the tax preparation process. Before using financial information to prepare a return, the CPA firm may need to investigate account balances and resolve outstanding bookkeeping issues.
An outsourced bookkeeping team can help prepare these records by:
- Recording transactions from bank statements and supporting documents.
- Reviewing income and expense classifications.
- Reconciling bank and credit card accounts.
- Identifying duplicate or missing entries.
- Reviewing accounts payable and receivable balances.
- Preparing general ledger reports and supporting schedules.
Consider a business whose accounting software shows a different cash balance from its bank statement. The difference may relate to outstanding checks, deposits in transit, duplicate entries, or transactions that have not been recorded.
The bookkeeping team can investigate the difference, document the reconciliation items, and report unresolved questions to the CPA firm.
This gives the firm's internal professionals a clearer view of the records before they proceed with tax preparation.
3. Give Internal Staff More Time for Tax and Client Work
Bookkeeping and tax preparation require different skills. Bookkeeping involves recording transactions and reconciling accounts, while tax preparation requires a closer look at financial details, tax knowledge, and regular communication with clients.
When in-house accountants spend too much time on routine bookkeeping, they have less time to focus on tax preparation and other important responsibilities.
Outsourcing selected bookkeeping activities can create a clearer division of work.
For example, an external team can prepare bank reconciliations, update general ledger accounts, and organize supporting documents. The CPA firm's internal accountant can review the reconciliations, investigate unusual balances, and communicate with the client about missing information.
The objective is to allocate work according to the responsibilities and expertise required, rather than transferring every accounting activity outside the firm.
4. Keep Ongoing Bookkeeping From Falling Behind
Tax preparation takes priority during filing season, but businesses still need to manage their daily operations.
They still make payments, receive customer deposits, issue invoices, purchase supplies, and process payroll. These transactions need to be recorded in the appropriate accounting period.
If recurring bookkeeping work is postponed until after tax season, clients may face a growing backlog of transactions and incomplete financial reports.
With an outsourced team handling routine bookkeeping, the CPA firm's staff can spend more time preparing tax returns and meeting filing deadlines
For example, the firm may maintain a monthly bookkeeping schedule for selected clients while assigning year-end cleanup and reconciliation work to an external team. This helps separate recurring accounting responsibilities from additional seasonal work.
The arrangement should include clear submission deadlines, reconciliation schedules, and procedures for escalating incomplete records.
5. Access Accounting Support Without Expanding Internal Infrastructure
When firms hire additional staff, they need to consider the full cost of employment. This includes not only salaries but also recruitment, training, software, equipment, and day-to-day supervision.
Outsourcing gives firms extra bookkeeping support without the need to hire additional employees whenever workloads increase.
However, outsourcing is not automatically less expensive. The firm should compare the complete cost of both arrangements, including provider fees, communication time, quality reviews, software requirements, and management responsibilities.
A good outsourcing arrangement should fit the firm's needs, provide reliable support, and maintain proper accounting controls. Price should be only one factor in the decision.
Which Bookkeeping Tasks Can CPA Firms Outsource During Tax Season?
Outsourcing allows CPA firms to hand over routine bookkeeping work without giving up control of financial reviews and important client decisions.
Firms should clearly explain their accounting processes and reporting needs before the outsourced team starts working.
| Bookkeeping Activity | Work Performed by the Outsourced Team |
|---|---|
| Transaction Recording | Enter and categorize transactions using the firm's instructions and supporting records |
| Bank Reconciliation | Match recorded transactions with bank statements and investigate differences |
| Credit Card Reconciliation | Review charges, payments, credits, and outstanding balances |
| Accounts Payable | Record supplier invoices and maintain payable records. |
| Accounts Receivable | Record customer invoices and payments and identify outstanding balances. |
| General Ledger Maintenance | Review account postings and prepare ledger reports. |
| Catch-up Bookkeeping | Organize and record transactions for periods with incomplete bookkeeping. |
| Month-end Closing Support | Prepare reconciliations, schedules, and reports for internal review. |
| Year-end Bookkeeping | Organize closing records and prepare agreed supporting schedules. |
The exact responsibilities depend on the engagement scope, accounting software, client requirements, and the CPA firm's internal procedures.
How Bookkeeping Activities Support Tax Preparation
Every bookkeeping task helps keep financial records accurate and ready for tax preparation.
Bank and credit card reconciliations: Helps identify differences between accounting records and bank statements, allowing the team to review and resolve any issues before finalizing the accounts.
Accounts payable: Helps keep supplier invoices, payment records, and outstanding bills organized so the firm can easily review balances and supporting documents.
Accounts receivable: Provide information about customer invoices, receipts, and outstanding balances. Differences between recorded sales and customer payments can be reviewed and resolved.
General ledger maintenance: Helps identify unusual transactions, incorrect account classifications, and balances that need to be reviewed.
Year-end supporting schedules: Organizes financial information for selected balance sheet and income statement accounts so the CPA firm can review it.
These tasks help organize financial records for tax preparation, but they do not involve providing tax advice or making tax-related decisions. The CPA firm's professionals handle matters that require tax expertise or further review.
How Outsourced Bookkeeping Fits Into a CPA Firm's Tax Workflow
A well-managed outsourcing arrangement should follow the CPA firm's existing accounting process. Both teams need agreed responsibilities, document requirements, delivery dates, and review procedures.
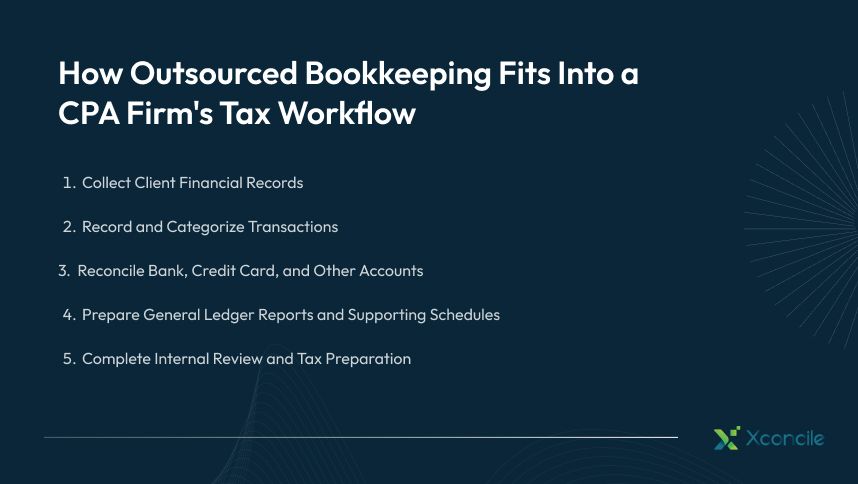
A practical workflow includes five stages.
1. Collect Client Financial Records
The CPA firm collects important financial documents, such as bank statements, credit card statements, invoices, receipts, payroll reports, and expense records.
The team should also check for any missing documents before starting the bookkeeping work.
This reduces unnecessary follow-ups and helps identify which periods and accounts are ready for processing.
2. Record and Categorize Transactions
The outsourced bookkeeping team records transactions in the firm's approved accounting system.
Each entry should follow the firm's chart of accounts and classification instructions. Transactions that lack sufficient supporting information should be flagged rather than assigned an arbitrary category.
3. Reconcile Bank, Credit Card, and Other Accounts
The team compares accounting records with the relevant statements and supporting documents.
Differences should be reviewed and documented. Examples include missing entries, duplicate transactions, outstanding payments, and deposits that have not yet appeared on the bank statement.
For example, if a bank reconciliation shows a difference that cannot be explained by outstanding checks or deposits in transit, the team should document the amount and request the missing information rather than force the reconciliation to balance.
4. Prepare General Ledger Reports and Supporting Schedules
After the agreed bookkeeping work is completed, the team prepares the required reports.
These may include:
- General ledger details.
- Trial balance information.
- Bank reconciliation reports.
- Accounts payable and receivable summaries.
- Selected balance sheet supporting schedules.
- Lists of unresolved transactions.
The reports provide a structured basis for the firm's review.
5. Complete Internal Review and Tax Preparation
The CPA firm's team reviews the completed bookkeeping work, checks any pending issues, and decides whether further adjustments are needed.
The firm can then use the reviewed financial records to prepare tax returns, following its usual procedures and professional responsibilities.
This division of work helps maintain accountability while allowing the external team to support the firm's bookkeeping workload.
How CPA Firms Maintain Accuracy and Protect Client Data
Outsourced bookkeeping teams may need access to financial records and sensitive taxpayer information. CPA firms should review the provider's accounting processes and data security measures before sharing this information.
Establish Clear Accounting Review Procedures
A reliable process should clearly explain how bookkeeping tasks are completed, reviewed, documented, and approved.
Useful controls include:
- Written transaction classification instructions.
- Standard bank and credit card reconciliation procedures.
- Supporting documentation for adjustments.
- Exception reports for unresolved transactions.
- Review checklists for completed deliverables.
- Defined procedures for correcting errors.
For example, a completed bank reconciliation should identify the statement period, relevant balances, outstanding items, and any differences that need to be reviewed.
The firm should clearly assign responsibility for preparing and reviewing each reconciliation. Both the internal and outsourced teams should understand their roles.
Use Appropriate Information Security Controls
Tax and accounting firms handle confidential information, including financial records, personal details, and taxpayer information.
Federal data-security requirements apply to covered tax professionals, who must maintain a Written Information Security Plan (WISP) appropriate to their business and the information they handle.
The IRS's guidance on protecting taxpayer data with a WISP discusses risk assessments, safeguards, employee training, and service-provider oversight.
Before sharing client information, CPA firms should assess:
- Restricted user permissions and system access.
- Multifactor authentication.
- Secure document transfer and storage.
- Employee confidentiality procedures.
- Data retention and deletion policies.
- Incident reporting and response procedures.
- Contractual responsibilities of the service provider.
The firm should also evaluate applicable federal and state privacy requirements. The FTC's Safeguards Rule provides additional requirements for covered financial institutions, including oversight of service providers.
Understand Section 7216 Before Sharing Taxpayer Information
Internal Revenue Code Section 7216 restricts the unauthorized use or disclosure of tax return information by tax return preparers.
When a CPA firm shares information with an external bookkeeping or accounting provider, it should first determine whether the records contain tax return information protected by Section 7216. The applicable rules depend on the recipient, the recipient's location, the relationship between the recipient and the tax return preparer, and the purpose of the disclosure.
Treasury Regulation §301.7216-2 includes specific provisions for disclosures involving recipients outside the United States. The firm should review the applicable rules and obtain tax or legal advice before sharing protected information.
A general confidentiality agreement should not be treated as automatic permission to disclose taxpayer information.
For further guidance, firms can review the IRS Section 7216 Information Center and the applicable regulations, including 26 CFR §301.7216-2.
What Should CPA Firms Evaluate Before Choosing a Bookkeeping Outsourcing Partner?
The success of outsourced bookkeeping depends on the provider's accounting expertise, work processes, data security, and ability to meet the CPA firm's expectations.
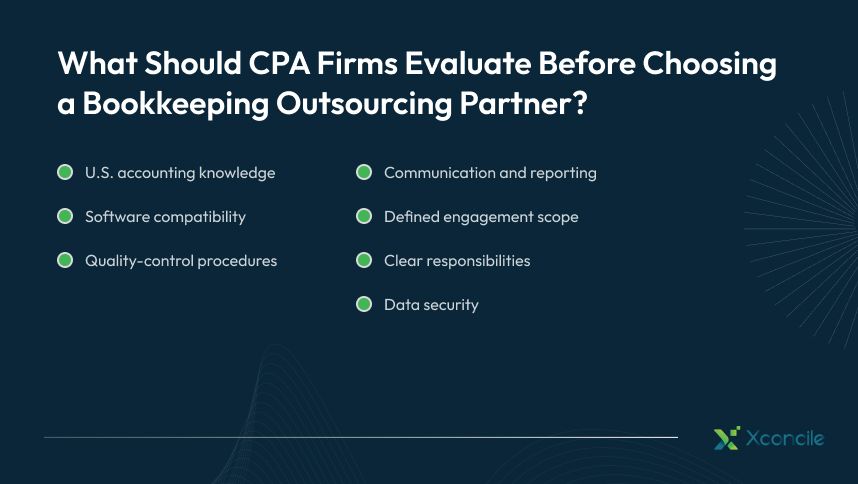
U.S. accounting knowledge: The provider should be experienced in U.S. bookkeeping practices and understand account classifications, reconciliation procedures, and financial reporting requirements. Ask whether the team can follow your chart of accounts and existing accounting procedures.
Software compatibility: Confirm that the team can work within the firm's approved accounting platforms and access requirements. Ask how the provider handles software permissions and client-specific workflows.
Quality-control procedures: Ask how transactions, reconciliations, adjustments, and supporting schedules are checked before delivery. Confirm who reviews completed work and how errors are corrected.
Data security: Review the provider's access controls, security policies, employee training, and contractual safeguards. Ask how the provider controls access to sensitive data and reports any security incidents.
Communication and reporting: Set clear communication guidelines, including a main point of contact, reporting schedule, process for raising concerns, and timelines for responding to questions. Make sure both teams understand how missing records and unresolved transactions should be reported.
Defined engagement scope: Confirm which bookkeeping tasks are included, how additional work is handled, and how changes in transaction volumes will be managed.
Clear responsibilities: Document which activities the outsourced team can perform and which decisions, reviews, and approvals remain with the CPA firm.
A limited initial engagement can help the firm assess the provider's work quality, communication, and ability to follow established accounting procedures before expanding the arrangement.
Conclusion
Tax season places additional demands on CPA firms, particularly when several clients need year-end bookkeeping support at the same time.
Outsourced bookkeeping can provide additional capacity for transaction recording, bank and credit card reconciliations, accounts payable and receivable, general ledger maintenance, and year-end supporting schedules.
However, successful outsourcing requires more than assigning routine tasks to an external team. CPA firms need documented accounting procedures, clear responsibilities, appropriate review controls, and safeguards for confidential client information.
Xconcile provides outsourced accounting and bookkeeping services for U.S. businesses and CPA firms. Its services include bookkeeping, accounts payable and receivable, reconciliations, and month-end accounting support.
For CPA firms needing additional bookkeeping support, an effective outsourcing process can help manage accounting work while internal professionals oversee client communication, reviews, and tax-related decisions.
Frequently Asked Questions
- 1. Why do CPA firms outsource bookkeeping during tax season?
- CPA firms outsource bookkeeping to manage increased workloads, maintain client accounting records, and access additional processing capacity. This allows internal professionals to focus on tax preparation, client communication, and reviewing financial information.
- 2. What bookkeeping tasks can CPA firms outsource?
- Common tasks include transaction recording, bank and credit card reconciliations, accounts payable, accounts receivable, general ledger maintenance, catch-up bookkeeping, and preparation of year-end supporting schedules.
- 3. Is outsourced bookkeeping suitable for small CPA firms?
- Yes. Small CPA firms can use outsourced bookkeeping to access additional accounting support without immediately recruiting permanent employees. The arrangement should match the firm's workload, software, budget, and review requirements.
- 4. How does outsourced bookkeeping support tax preparation?
- Outsourced bookkeeping helps organize financial records, reconcile accounts, identify discrepancies, and prepare supporting schedules. The CPA firm's professionals can then review the records and address outstanding issues before completing tax preparation.
- 5. How can CPA firms protect client data when outsourcing bookkeeping?
- Firms should assess service-provider security controls, restrict system access, use secure file-sharing methods, maintain confidentiality procedures, and review applicable privacy requirements. Covered tax professionals must also maintain an appropriate Written Information Security Plan.
- 6. Does outsourcing bookkeeping mean giving up control of client accounts?
- No. CPA firms can define the outsourced team's responsibilities, system permissions, reporting procedures, and review requirements. Client relationships, professional judgment, and agreed approval responsibilities can remain with the firm's internal team.
- 7. When should CPA firms start outsourcing bookkeeping before tax season
- Firms should evaluate their workload and establish outsourcing arrangements before their busiest period. Starting early gives both teams time to transfer process instructions, configure access, test deliverables, and establish review procedures.


